
The Moyo family’s school fees plan
With their daughter starting secondary school in six years, the Moyos set a goal, built an emergency fund and chose a unit trust. Small, regular amounts did the rest.
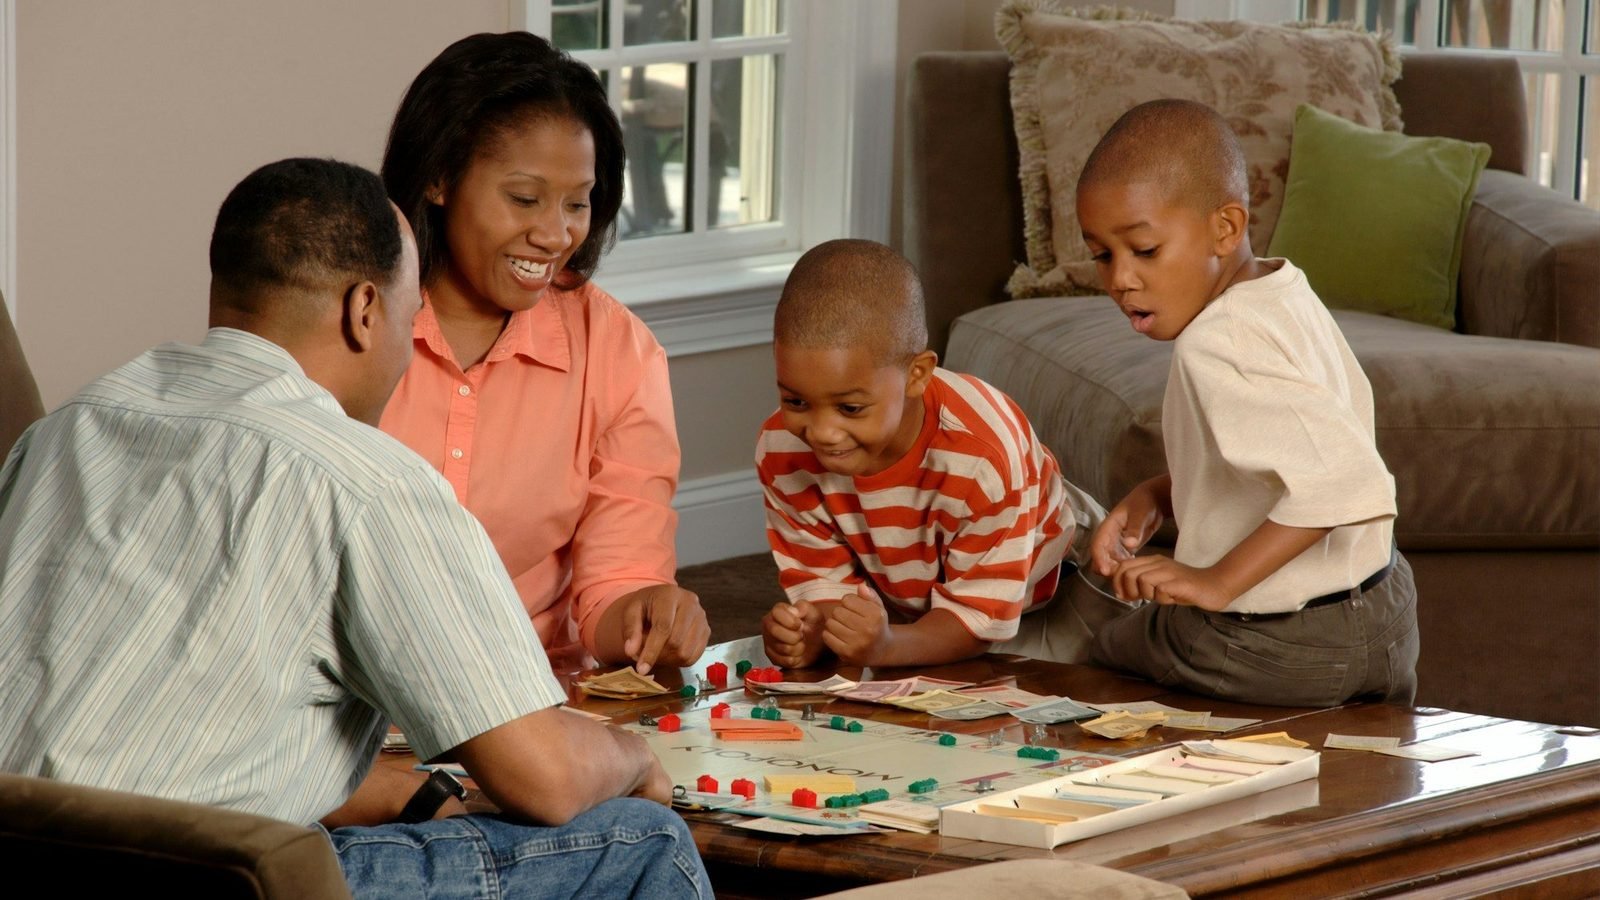
Every January, Mr and Mrs Moyo in Bulawayo used to dread the same thing: school fees. Their daughter Nokuthula is seven. When she starts boarding school in six years, they will need a lump sum they have never had at once.
Turning a worry into a goal
They sat down one evening and wrote it as a goal they could plan for: US$3,000 in six years for Nokuthula’s first year of secondary school. Using the savings goal calculator, they saw that at a cautious 6% a year they would need to put aside a little over US$35 a month.
Foundations first
Before investing anything, the Moyos built an emergency fund of three months’ expenses in a savings account. “The car broke down twice that year,” Mrs Moyo laughs. “Without the emergency fund, we would have raided the school money.”
Choosing how to invest
Neither of them had time to pick individual shares. They read about unit trusts and spoke to two registered managers listed on the SECZ register. They compared:
- what each fund invested in, and how much its value had moved up and down in the past;
- the initial and annual fees, in writing;
- how quickly they could get their money out.
They chose a balanced fund and set up a monthly debit order of US$40 – a little more than the calculator suggested, to give themselves room for a bad year.
“Forty dollars didn’t feel like much,” says Mr Moyo. “But it went in every month, whether we remembered or not.”
Three years later
One year the fund fell in value, and Mr Moyo wanted to stop. Mrs Moyo pointed out that their monthly US$40 was now buying more units at the lower price. They kept going. Halfway to their goal, they review the fund once a year and plan to move the money into a lower-risk money market fund in the final year, so a late fall in the market cannot spoil the plan.
What the Moyos teach us
- A specific goal, with an amount and a date, is easier to reach than a vague wish.
- An emergency fund protects your investments from life’s surprises.
- Regular, automatic contributions beat waiting for the “right time”.
- Move money you need soon into lower-risk investments as the date approaches.
This story is an illustration. The people and figures are made up, but the situations are ones investors in Zimbabwe really face.
More stories
Rudo and the forex club
A WhatsApp group promised 30% a month. Rudo’s cousin was already “earning”. Here is what happened next, and the signs she nearly missed.
Tendai buys his first shares
A graduate in Gweru wanted to own part of the companies he used every day. He learned how to choose a stockbroker, what a broker’s note is, and why costs matter.
Farai and his grandfather’s shares
Clearing out an old trunk, Farai found broker’s notes from the 1990s. Were the shares still his family’s? And who was the caller asking for a “release fee”?